
Post Contents
Penfold is a UK digital pension provider offering personal, self-employed and workplace pensions. Its main strengths are flexible contributions, ready-made investment plans and straightforward digital account management.
However, Penfold is not the cheapest pension provider for smaller pension pots. It may also be unsuitable for experienced investors who want to select individual shares, funds or other investments.
| Feature | Penfold Pension Details |
| Pension Types | Personal, self-employed, director and workplace pensions |
| Standard Annual Fee | 0.75% on the first £100,000 |
| Sharia Plan Fee | 0.88% on the first £100,000 |
| Fee Above £100,000 | 0.40% or 0.53% for the Sharia Plan |
| Investment Style | Ready-made portfolios |
| Fund Managers | BlackRock and HSBC |
| Contributions | Regular and one-off payments |
| Pension Transfers | Available without a separate Penfold transfer fee |
| Tax Relief | Basic-rate relief normally added automatically to eligible personal contributions |
| Retirement Access | Usually from 55, rising to 57 from 6 April 2028 |
| Main Limitation | No individual share dealing or complete investment control |
Capital is at risk. Pension investments can rise or fall in value, and customers may receive less than they contributed.
Last Updated: 31.08.2026
What Is Penfold Pension?
Penfold is a digital pension platform designed to make retirement saving easier to understand and manage.
Customers can view their pension value, change contributions, select an investment plan and monitor performance through its online service and mobile app.
The company offers pensions for several types of UK saver, including:
- Self-Employed Workers
- Freelancers and Contractors
- Sole Traders
- Limited Company Directors
- Employees Using a Penfold Workplace Pension
- Individuals Opening an Additional Personal Pension
- Savers Combining Eligible Existing Pension Pots
Penfold does not provide a traditional self-directed investment account where customers can select individual shares. Instead, it offers a limited range of ready-made investment plans managed by established investment companies.
How Does Penfold Pension Work?
A customer opens an account, selects an available investment plan and chooses how much to contribute. Contributions can be made regularly or as one-off payments, depending on the type of pension and the customer’s circumstances.
Penfold then invests the money through the selected BlackRock or HSBC fund. The value of the pension changes according to contributions, charges and investment performance.
Customers can monitor:
- Current Pension Value
- Previous Contributions
- Investment Performance
- Selected Pension Plan
- Estimated Retirement Value
- Regular Payment Schedule
The projections displayed in a pension account are estimates rather than guaranteed retirement outcomes.
Personal and Self-Employed Pensions
A personal Penfold pension may suit someone who does not have access to a workplace scheme or wants to save alongside an existing workplace pension.
Its flexible contribution system may be particularly useful for self-employed workers whose income changes from month to month. Contributions can normally be adjusted, paused or supplemented with one-off payments.
Eligible personal contributions receive basic-rate tax relief. For example, when an individual contributes £80, the pension provider can normally claim £20 from HMRC, producing a gross contribution of £100.
Workplace and Company Director Pensions
Penfold also provides auto-enrolment workplace pensions for employers and their employees. Workplace fees may differ from the standard personal pension charge because Penfold can agree a separate rate with an employer.
Limited company directors may be able to make employer pension contributions directly from their businesses. These contributions can be tax-efficient, but their treatment depends on the company’s circumstances and whether the payments meet HMRC requirements.
Who Is Eligible for a Penfold Pension?
Penfold personal pensions are generally intended for UK residents aged 18 or over.
Applicants normally need to provide personal and tax information, including:
- Full Name and Address
- Date of Birth
- National Insurance Number
- UK Bank Account Details
- Proof of Identity
- Employment or Tax Status
Eligibility, contribution limits and tax relief can vary according to age, earnings and individual circumstances. Employees enrolled through a workplace pension will also be subject to their employer’s scheme rules.
Penfold Pension Fees and Charges
Penfold uses a percentage-based annual fee calculated from the value of the pension. Its published pension charges distinguish between the standard BlackRock-managed plans and the HSBC-managed Sharia Plan.
| Investment Plan | Fee on First £100,000 | Fee on Amount Above £100,000 |
| Penfold Plan | 0.75% | 0.40% |
| Lifetime Plans | 0.75% | 0.40% |
| Standard Plan | 0.75% | 0.40% |
| Sustainable Plan | 0.75% | 0.40% |
| Sharia Plan | 0.88% | 0.53% |
The lower rate applies only to the portion above £100,000. It does not reduce the charge on the entire pension pot.
For example, a £10,000 pension would cost approximately:
- £75 Per Year on a 0.75% Plan
- £88 Per Year on the 0.88% Sharia Plan
The actual amount deducted can change as the pension rises or falls in value.
Are There Additional Transfer or Withdrawal Fees?
Penfold does not charge separate fees for making contributions, switching between available plans or transferring a pension to or from the platform.
There is also no separate Penfold charge for retirement withdrawals. However, withdrawing pension money can create tax consequences and may reduce the amount that can be contributed to defined contribution pensions in the future.
Customers should check their personalised illustration and current terms before applying because charges and pension rules can change.
Penfold Pension Investment Plans
Penfold customers choose from ready-made investment plans rather than constructing a customised portfolio. These plans use underlying investments managed by BlackRock or HSBC.
| Plan | Investment Approach | Potentially Suitable For |
| Penfold Plan | Long-term multi-asset default plan managed by BlackRock | Savers wanting a ready-made default approach |
| Standard Lifetime Plan | Gradually adjusts investment risk as retirement approaches | Savers wanting automatic risk reduction |
| Sustainable Lifetime Plan | Lifetime approach using sustainability-focused investments | Savers wanting environmental considerations and automatic adjustments |
| Standard Plan | BlackRock portfolios with different risk levels | Customers choosing their own broad risk level |
| Sustainable Plan | ESG-focused BlackRock investments | Customers prioritising sustainability factors |
| Sharia Plan | HSBC Islamic Global Equity Index Fund | Customers requiring Sharia-compliant investing |
The Penfold Plan became the provider’s default investment option in February 2025. It was designed specifically for long-term pension saving and replaced the previous default arrangement for new customers.
Can Customers Select Individual Investments?
Penfold does not offer individual share dealing. Customers select from its available plans, while BlackRock or HSBC manages the underlying investments.
This simplified approach can help less experienced investors avoid selecting individual assets. The trade-off is less investment freedom than a conventional self-invested personal pension offering a wider choice of shares, exchange-traded funds and investment funds.
How Has Penfold Pension Performed?
Performance varies between plans, risk levels and investment periods. A higher-risk equity-focused option can produce stronger growth during favourable markets but may also experience larger falls.
When reviewing performance, customers should consider:
- The Exact Plan Being Assessed
- Whether Returns Are Before or After Fees
- The Period Covered by the Figures
- The Level of Investment Risk
- Whether Figures Are Actual or Simulated
- Performance Against an Appropriate Benchmark
Past performance does not guarantee future returns. Simulated results for a recently introduced plan should not be presented as though they were returns achieved by actual customers.
Penfold Pension Pros and Cons
| Advantages | Disadvantages |
| Simple digital pension management | No individual share dealing |
| Flexible regular and one-off contributions | Limited range of ready-made plans |
| Options for self-employed workers and directors | Standard fee may be higher than some low-cost providers |
| Existing pensions can be combined | No personalised financial advice |
| Sustainable and Sharia-compliant choices | Investments can fall in value |
| No separate Penfold transfer fee | Transferring some pensions may mean losing valuable guarantees |
| Fees fall on the portion above £100,000 | Percentage fees increase as the pension pot grows |
Tax Relief and Penfold Contribution Rules
Eligible personal contributions normally receive basic-rate tax relief at source. Higher-rate and additional-rate taxpayers may be able to claim further relief, depending on their location, taxable income and individual circumstances.
The standard pension annual allowance is £60,000 for the 2026/27 tax year. This allowance applies across a person’s private pensions rather than separately to every account.
The current pension annual allowance rules explain that a lower allowance can apply to people with high incomes or those who have flexibly accessed taxable pension money.
Tax relief is also generally limited by relevant UK earnings. People without relevant earnings can usually receive tax relief on gross personal contributions of up to £3,600 each tax year, subject to eligibility.
Tax treatment depends on personal circumstances and may change.
Can Existing Pensions Be Transferred to Penfold?
Penfold allows customers to transfer and combine eligible existing pension pots. The customer normally provides the previous provider’s name and policy details, after which Penfold can assist with the transfer process.
Combining pensions can make retirement savings easier to monitor, but transferring is not always suitable.
A transfer could cause the saver to lose:
- Guaranteed Annuity Rates
- Protected Pension Ages
- Guaranteed Investment Returns
- Enhanced Tax-Free Cash Rights
- Employer Contributions
- Valuable Exit or Loyalty Benefits
Defined benefit pensions and pensions containing safeguarded benefits require particular care. Financial advice may be legally required before certain safeguarded benefits worth more than £30,000 can be transferred.
Is Penfold Pension Safe and Regulated?
Penfold Savings Limited appears on the Financial Conduct Authority register under reference number 826097. FCA authorisation means the company is permitted to conduct specified regulated activities and must follow applicable regulatory requirements.
FCA authorisation does not mean that investment returns are guaranteed or that a pension cannot fall in value.
Penfold states that pension assets are held separately from the company’s operational finances. Investments are managed through providers such as BlackRock and HSBC rather than being held as ordinary company money.
FSCS protection may apply if an authorised provider, investment manager or bank fails and cannot return eligible assets. The amount and type of protection depend on the investment structure and circumstances of the claim.
The default Penfold Plan may receive broader provider-failure protection than some of the other options. Customers should confirm the protection attached to their selected plan instead of assuming every plan has identical cover.
The FSCS does not compensate customers for ordinary investment losses caused by markets falling.
How to Set Up a Penfold Pension Account?
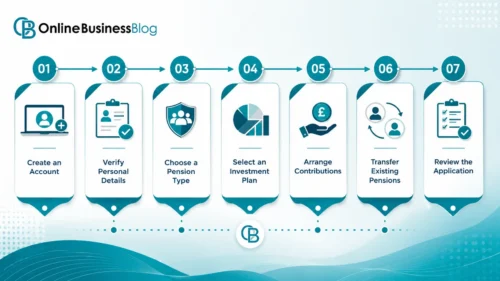
Setting up a Penfold pension is completed digitally.
1. Create an Account
Provide an email address and basic personal information.
2. Verify Personal Details
Submit the required identity, address, banking and tax information.
3. Choose a Pension Type
Select a personal, self-employed or director pension where applicable.
4. Select an Investment Plan
Compare each plan’s risk level, investment approach and fees.
5. Arrange Contributions
Set up regular payments, make a one-off contribution or use both options.
6. Transfer Existing Pensions
Provide the details of any eligible pensions that need to be combined.
7. Review the Application
Check the fees, investment choice, retirement age and risk information before confirming.
Pension transfers can take longer than opening a new account, particularly when the previous provider uses manual processes or requires additional checks.
Who Is Penfold Pension Best For?
Penfold may be suitable for:
- Self-Employed People Wanting Flexible Contributions
- Freelancers With Irregular Income
- Limited Company Directors Making Business Contributions
- Savers Who Prefer Ready-Made Investments
- People Combining Several Eligible Pension Pots
- Employers Looking for a Digital Workplace Pension
- Customers Seeking Sustainable or Sharia Options
It may be less suitable for:
- Experienced Investors Wanting Individual Shares
- Savers Prioritising the Lowest Possible Platform Fee
- People Requiring Personalised Financial Advice
- Customers With Defined Benefit Pensions
- People Holding Pensions With Valuable Guarantees
- Investors Wanting a Large Selection of Funds
Penfold Pension Alternatives
The most appropriate alternative depends on whether the saver values low fees, pension consolidation, investment choice or simple account management.
| Provider | Main Difference Compared With Penfold |
| PensionBee | Offers a wider range of ready-made plans and focuses heavily on pension consolidation |
| Moneybox | Combines pensions with other app-based saving and investment products |
| Nest | Government-established workplace scheme with a contribution charge and lower ongoing fee |
| Vanguard | Offers low-cost pension investing but a different service and investment selection |
| AJ Bell | Provides considerably more investment choice for experienced investors |
| Interactive Investor | Uses subscription-based pricing that may suit some larger portfolios |
Fees should be compared using the customer’s actual pension value. A provider that appears cheaper for a £10,000 pot may not remain cheaper when the balance becomes significantly larger.
Penfold Pension Review Verdict
Penfold offers straightforward pension management for self-employed workers, company directors, employees and individuals who prefer ready-made investment plans.
Flexible contributions, free pension transfers and simple digital access are its most notable strengths.
Its standard 0.75% annual charge is easy to understand but is not the lowest available for smaller pension pots.
The platform also offers less control than a full SIPP because customers cannot select individual shares or build a completely customised portfolio.
Penfold may therefore suit someone who values convenience and guided investment choices more than having the broadest selection of investments.
Customers should compare the fees, available plans and any benefits attached to existing pensions before transferring.
This article provides general information and does not constitute personalised financial advice.
Frequently Asked Questions
Is Penfold a SIPP?
Penfold provides a personal pension with ready-made investment plans. It does not offer the extensive individual investment selection associated with many full DIY SIPPs.
How Much Does Penfold Charge?
Most direct customers pay 0.75% annually on the first £100,000. The Sharia Plan costs 0.88%, with lower rates applying to the portion above £100,000.
Is There a Minimum Penfold Pension Contribution?
Penfold supports flexible regular and one-off contributions. Customers should confirm any current payment limits during the application process.
Can Self-Employed People Use Penfold?
Yes. Penfold offers pensions for freelancers, contractors, sole traders and other self-employed workers.
Can an Existing Workplace Pension Be Transferred?
Many defined contribution workplace pensions can be transferred, but savers should check for guarantees, protected rights and exit conditions first.
When Can Money Be Withdrawn From Penfold?
Pension money is normally accessible from age 55. The normal minimum pension age is scheduled to rise to 57 from 6 April 2028, subject to limited exceptions.
Can Money Be Lost in a Penfold Pension?
Yes. Penfold pensions are investments, so their value can fall as well as rise. FSCS protection does not cover ordinary losses caused by investment performance.
